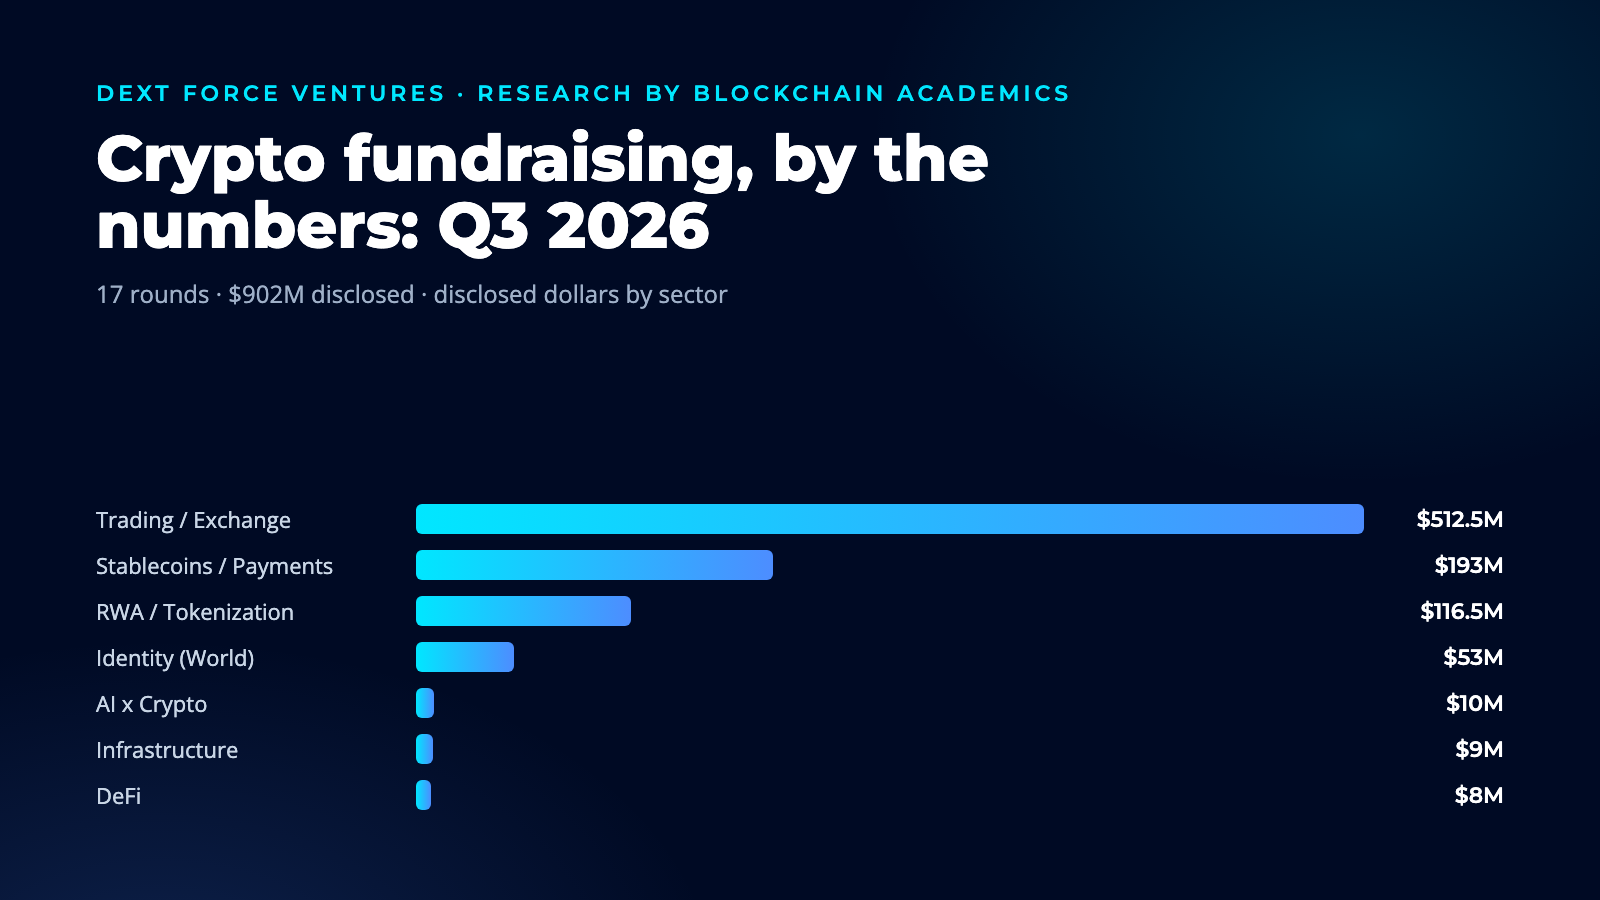
Every quarter tells you where the people writing checks think crypto is going. We went through every funding round Blockchain Academics covered between July 1 and September 30, 2026, checked each one against the original report, and counted.
The short version: 17 rounds, $902M in disclosed capital, and a clear message. Money is flowing to the rails that move dollars, not to the apps on top of them.
The headline numbers
- 17 rounds announced in Q3 2026. 14 disclosed an amount, 3 did not.
- $902M disclosed in total.
- $37.5M median round. The average is $64.4M, pulled up by one very large deal.
- July was the busiest month: 7 rounds and $526M. August brought 5 rounds and $151M, September 5 rounds and $225M.
A note on method: this is the set of rounds covered by Blockchain Academics, not a census of every raise in the market. It is a curated view of the deals that made news, which is exactly why it is useful for reading direction.
Wall Street bought the exchanges
The two largest checks did not come from crypto funds. They came from traditional finance.
- Citadel Securities invested $400M in Crypto.com at a $20B valuation, the exchange's first institutional funding.
- Nasdaq put $100M into Kraken at a $21B valuation, tied to a tokenized equities partnership.
Those two strategic stakes account for 55% of every disclosed dollar in the quarter. Take them out and the quarter is $402M across 12 disclosed rounds, with a median of $24.75M. The signal is not the size of the checks. It is who wrote them. Market makers and exchange operators are no longer watching crypto venues from the outside; they are buying into them.
Stablecoins and payments led the venture rounds
Strip out the exchange stakes and the venture story is about money movement:
- Kast raised $80M for stablecoin banking.
- Fasset raised a $68M Series C led by SBI Group at a $1B valuation.
- Velocity raised a $38M Series A led by Dragonfly and FirstMark, with Coinbase, Ripple and Capital One Ventures participating.
- Pact Labs raised a $7M Series A from Tether for stablecoin payroll.
Four stablecoin and payments rounds brought in $193M, second only to the exchanges. Add tokenization and settlement, where RQD* Clearing raised $74M and HIFI raised a $37M Series A, and 9 of the quarter's 17 rounds went to infrastructure for moving and settling value.
The biggest transaction of the quarter was not a round at all: Mastercard completed its $1.8B acquisition of BVNK, a stablecoin infrastructure company. When a card network pays that much for stablecoin rails, the venture rounds above stop looking speculative.
What got no money
Just as telling is what is missing. Across the quarter's covered rounds:
- Gaming and NFTs: zero rounds.
- AI x crypto: one round, TrueDAO's $10M strategic raise led by Brevan Howard Digital.
- DeFi: two small rounds, with $8M disclosed.
The capital that chased narratives in previous cycles is now concentrated in businesses with revenue paths a bank would recognize.
Nobody backed the same team twice
26 investors are named across the quarter's rounds, and not one appears in more than one deal. Some of that is coverage: four rounds named no investors at all. But it also reflects a market where conviction is selective. Funds are writing fewer, larger checks into specific theses rather than spraying across a sector.
What this means for founders
- Payments, settlement and tokenization are fundable now. If your product moves or settles value with a clear path to revenue, the market is open.
- Strategic money is real money. The largest checks came from operators who want a partnership, not just a return. Know what you offer them beyond equity.
- Narrative alone is not enough. The categories that raised on story in past cycles were largely absent this quarter.
Our take
At DEXT Force Ventures we read Q3 as the market maturing in public. The capital is backing infrastructure that institutions can plug into, and the institutions themselves are now writing the checks. For founders building real rails, the window is open; for those building on hype, it has rarely been narrower.
Data: rounds announced July 1 to September 30, 2026 as covered by Blockchain Academics news, each checked against the original article. Amounts are as reported; three rounds did not disclose a size. Market-wide totals are higher than this covered set.
Research and data by Blockchain Academics.